For people on SSDI or SSI
Not a risk. Not a trap. The rules that decide what happens to your check are knowable, and you are allowed to see them before you take the step instead of finding out afterward.
A lintel is the beam that carries the weight above a doorway so people can walk through it. That is the whole idea.
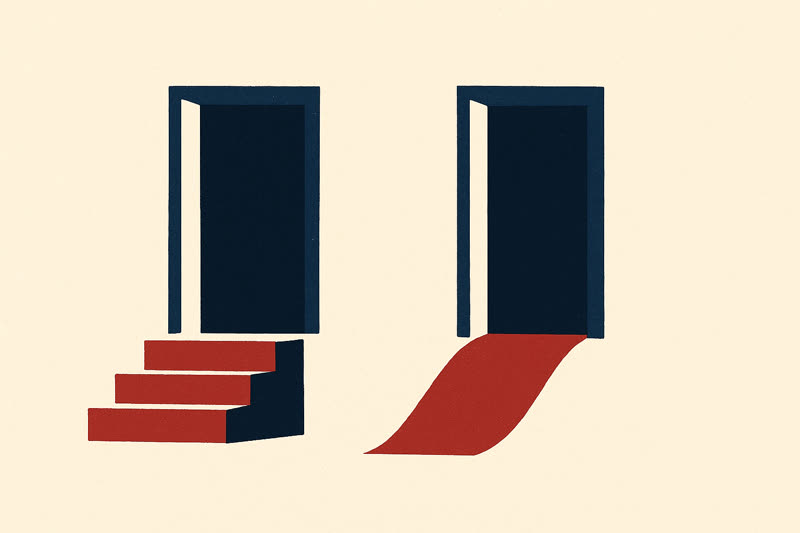
Two doors, not one form. Almost nobody in either program is told the difference, and it is the difference that decides everything: SSDI has a genuine cliff and SSI has none at all.
You paid in. There is a real cliff.
Earn above the substantial gainful activity line after your trial work period and the check does not shrink — it stops. Lintel shows you the exact month it stops, the exact size of the drop, and the total across four years, on your own figures.
Then the parts that survive it: 93 months of Medicare, Expedited Reinstatement, and the way back in.
Enter the SSDI door → Door twoNeeds based. There is no cliff at all.
The payment steps down gradually as you earn — roughly a dollar for every two, after exclusions — and it does not fall off an edge. Most people are never told this. Lintel draws the whole slope, including the point where the payment reaches zero and what happens then.
Then what is protected anyway: 1619(b) Medicaid continuation, the student earned income exclusion, and ABLE.
Enter the SSI door →People are not staying out of work because the rules trapped them. They are staying out of work because nobody has ever shown them the rules, so the safest-looking move is not to move.
27.9%
Of nonworking beneficiaries named losing cash or health benefits as the reason.
2015 National Beneficiary Survey
6.5%
Of a 1996 award cohort ever had benefits suspended for work — against 28% who worked at all. The thing being feared happened to a fraction of the people who risked it.
Liu and Stapleton, ten-year follow-up
Lead with this, because it is the part that changes the decision. These are not favors. They are already in the law, already funded, and already yours.
On SSI, your Medicaid can continue after the cash payment reaches zero, up to a threshold that is set state by state. Losing the check does not automatically mean losing coverage.
On SSDI, Medicare continues for seven years and nine months after the trial work period ends, even once the cash benefit has stopped.
If work does not hold, you do not start over. There is a defined route back in without filing a brand new application.
Self-employment is judged on three separate tests, not on gross revenue. A Plan to Achieve Self-Support can shelter the money you are putting into getting the business off the ground.
A savings account that does not count against the resource limit, so having money set aside stops being a reason to lose eligibility.
They often are, and it does not disqualify anyone from anything on this page. Recovery is the path with the rewards on it, never the condition standing in front of the benefit — that rule holds across everything in this series.
The recovery model has its own framework, its own applications, and its own way in.
Go to the recovery model →4 of 52
1619(b) thresholds verified against a primary source. The other 48 are shown as open rather than filled in with plausible numbers, because a wrong threshold would tell someone their health coverage is safe when it is not.
Every factual cell in the app says what it is — verified, likely, unverified, or open — and only verified items count toward a finding.